- Retail Insurance
- Business Insurance
- Resources
- Claims


Third-party bike insurance is a liability-only policy that covers injury, death or property damage of a third party in an accident caused by the policyholder’s bike. This policy does not cover damage to the policyholder’s own vehicle.
"Third party" refers to whoever isn't part of the insurance contract:
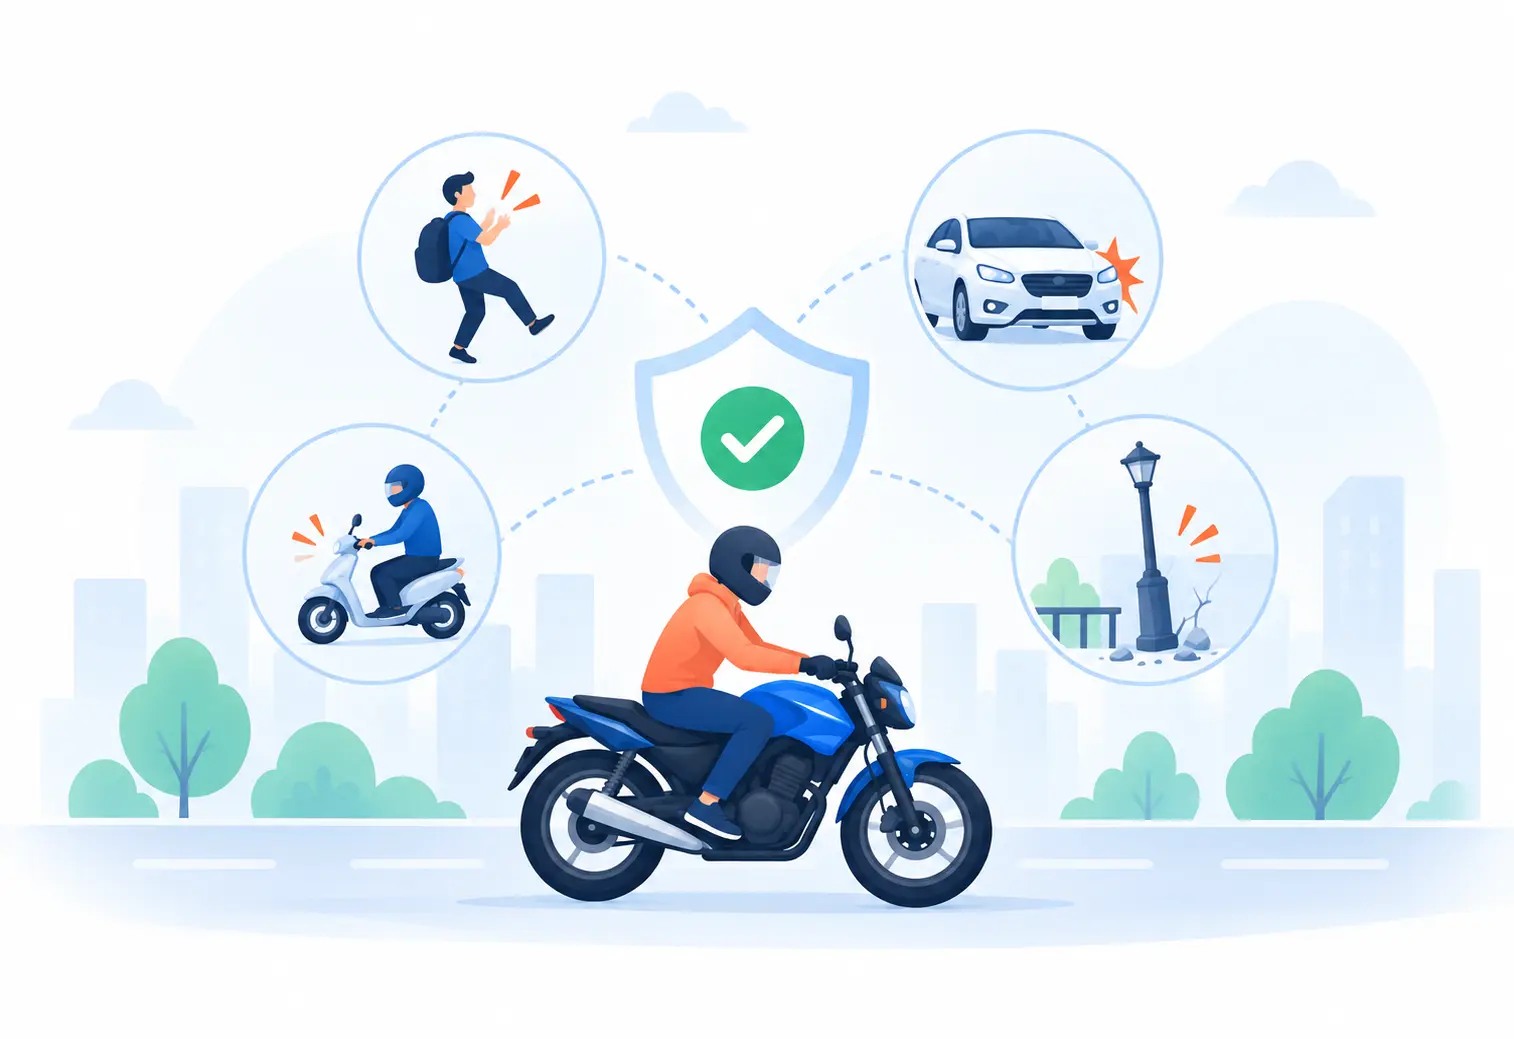
Section 146 of the Motor Vehicles Act, 1988 makes third party insurance compulsory for every motor vehicle on Indian roads, two-wheelers included. For a 2 wheeler third party insurance policy, the law exists so that accident victims are compensated.
2026 Regulatory Update The Supreme Court directed on 4 August 2026 that third-party insurance for new two-wheelers should be purchased for six years instead of the earlier five-year period. The Court also directed IRDAI to issue the necessary directions for implementation. Until the applicable implementation directions are issued, customers should verify the tenure applicable to their new vehicle at the time of purchase.
Your bike collides with a parked car while turning at a junction. The bumper is damaged, and the driver, who had stepped out, suffers a minor injury.
The car owner and the driver are the third party here. Your third party bike insurance answers their claim, not the damage to your own bike, because the policy only covers what you owe others.
Compensation claims arising from motor accidents are handled by a Motor Accident Claims Tribunal (MACT). Depending on the circumstances, the claimant may need to approach the tribunal directly.
Don’t ride uninsured
Riding without valid third-party insurance can attract a traffic fine of ₹2,000 or more
IRDAI prescribes the premium rates applicable to motor third-party liability insurance. These rates may be revised through regulatory notifications.
| Engine Capacity | 1-Year Premium | 5-Year Premium |
|---|---|---|
| Engine CapacityUp to 75cc | 1-Year Premium₹538 | 5-Year Premium₹2,901 |
| Engine Capacity75cc to 150cc | 1-Year Premium₹714 | 5-Year Premium₹3,851 |
| Engine Capacity150cc to 350cc | 1-Year Premium₹1,366 | 5-Year Premium₹7,365 |
| Engine CapacityAbove 350cc | 1-Year Premium₹2,804 | 5-Year Premium₹15,117 |
| Motor Power | 1-Year Premium | 5-Year Premium |
|---|---|---|
| Motor PowerUp to 3 kW | 1-Year Premium₹457 | 5-Year Premium₹2,466 |
| Motor Power3 kW to 7 kW | 1-Year Premium₹607 | 5-Year Premium₹3,273 |
| Motor Power7 kW to 16 kW | 1-Year Premium₹1,161 | 5-Year Premium₹6,260 |
| Motor PowerAbove 16 kW | 1-Year Premium₹2,383 | 5-Year Premium₹12,849 |
Note: These figures are base premiums; insurers add 18% GST at checkout. Rates are set under IRDAI's regulatory framework and can change with a fresh notification, so confirm the current figure before you renew.
Required to ride legally on Indian roads as per law.
Covers injury, death, or property damage your bike causes to others.
Shields you from paying compensation out of pocket after an accident.
Medical costs and compensation for third-party injury or death, as decided by the Motor Accident Claims Tribunal (MACT).
Third-party property damage is covered up to ₹7.5 lakh under motor third-party liability insurance. The policyholder can opt to restrict this cover to ₹6,000 for a lower liability-only premium.
Covers injury caused to a third party in an accident involving the insured bike.
Provides compensation for third-party death, with the amount determined by the Motor Accident Claims Tribunal (MACT).
Covers third-party permanent or partial disability resulting from a covered accident.
Covers damage caused to third-party property, subject to the applicable ₹7.5 lakh limit.
Covers eligible legal liabilities and defence costs arising from a third-party claim, including representation before the MACT.
Provides up to ₹15 lakh cover for accidental death or specified disabilities of the owner-driver, subject to policy terms.
Damage to your bike is not covered under a third-party-only policy.
Theft of the insured bike is outside the scope of third-party cover.
Damage to your bike caused by fire, floods, storms or other natural events is not covered.
Your own injuries beyond the applicable CPA protection are not covered unless you have separate personal accident protection.
Driving without a valid licence can affect the insurer’s rights and the insured’s liability depending on the circumstances and applicable law. Third-party claims are governed by the Motor Vehicles Act and the policy terms.
Claims arising while the rider is under the influence of alcohol or drugs are excluded.
Cover does not apply when the bike is used for commercial or hire purposes without the appropriate policy.
Incidents occurring outside the policy’s specified geographical area are not covered unless the required extension has been taken.
Indirect financial losses, such as loss of income while the bike is being repaired, are not covered.
Disclaimer: Coverage and exclusions can vary by insurer and policy wording. Always read your policy document in full, or check with the insurer directly, before assuming a specific claim will or won’t be covered.
Protect Yourself from Third-Party Liabilities
Stay financially protected against claims arising from third-party injury, death or property damage.
Compensation for a third party bike insurance claim depends on the nature of the loss, not on any sum insured you chose, since liability cover has no fixed sum insured for injury or death.
Unlimited liability coverage.
Up to ₹7.5 lakh.
Policyholders can opt for a ₹6,000 limit, which results in a lower liability-only premium.
Disclaimer: The MACT decides injury and death compensation under Section 166 of the Motor Vehicles Act, 1988, weighing the victim’s age, income, and extent of disability based on evidence presented.
Buyers comparing a two wheeler 3rd party insurance price against comprehensive bike insurance should refer to this table.
| Parameter | Third Party Bike Insurance | Comprehensive Bike Insurance |
|---|---|---|
| Covers own bike | Third Party Bike InsuranceNo | Comprehensive Bike InsuranceYes |
| Covers third-party liability | Third Party Bike InsuranceYes | Comprehensive Bike InsuranceYes |
| Legal requirement | Third Party Bike InsuranceMandatory | Comprehensive Bike InsuranceNot mandatory on its own |
| Premium | Third Party Bike InsuranceFixed by IRDAI, lower cost | Comprehensive Bike InsuranceVaries by insurer, IDV, and add-ons |
| Add-ons available | Third Party Bike InsuranceNone | Comprehensive Bike InsuranceZero depreciation, engine protection, roadside assistance, and more |
| Best suited for | Third Party Bike InsuranceRiders who only want legal coverage | Comprehensive Bike InsuranceRiders who wish to protect their own bike along with meeting legal requirements |
Buying 3rd party bike insurance online through Coverfox takes a few minutes:
Enter your bike’s registration number, model and registration location. For a new bike, select the “Bought a New Bike?” option.
Compare available third-party bike insurance options from different insurers. The third-party premium is based on the IRDAI-prescribed rates.
Choose the applicable policy period based on whether you are buying insurance for a new or existing bike.
Enter the policyholder and vehicle information needed to issue the policy.
Pay the applicable third-party bike insurance premium online through Coverfox.
Receive the issued policy document digitally at your registered email address.
The same process can be used for buying third-party scooter insurance online.
Third party bike insurance renewal on Coverfox follows a simple process:
Enter your bike registration number or existing policy details to fetch your policy information.
Check the third-party policy details, coverage period and applicable premium.
Verify the owner and vehicle information before proceeding with the renewal.
Complete the payment securely through Coverfox’s online payment gateway.
Get the renewed third-party bike insurance policy instantly on your registered email ID.
Two wheeler third party insurance renewal for a motorcycle or scooter is done before the expiry date to keep your coverage active and protect your NCB. A lapsed policy means riding illegally until it’s renewed.
If your bike is involved in an accident that causes injury, death or property damage to another person, you can initiate a third-party insurance claim. Here is the process to file a third party bike insurance claim:
Take evidence like photographs, witness contacts and note the vehicle number, the rider’s details, and the other vehicle’s insurance information.
Report the accident to the police and obtain an FIR where required.
Notify the relevant insurance company about the accident and share the available details.
Provide the policy details, FIR, photographs and any other documents requested during the claim process.
Where applicable, the third party can seek compensation through the Motor Accident Claims Tribunal.
Cooperate with the insurer and tribunal proceedings and provide any additional information requested.
If the claim is accepted, the compensation is determined and paid according to the applicable policy and legal provisions.
Whether you’re comparing the third party insurance bike price for a new purchase or hold an existing two wheeler 3rd party insurance policy up for renewal, here’s what Coverfox adds to the process:
Compare third-party bike insurance plans from 20+ insurers on one platform and choose a bike insurance policy based on your requirements.
Get an AI-powered insurance comparison experience that helps you assess policy options and make an informed choice.
Enter your bike details, compare available plans and buy your third-party bike insurance online without visiting an insurer’s branch.
Renew your existing third-party bike insurance online by entering your policy or vehicle details and completing the payment digitally with timely reminders.
Receive your policy document online after successful purchase or renewal, keeping it accessible when you need it.
Get assistance with claim intimation and the documentation required during the third-party claim process.
The bike insurance 3rd party price for 1 year depends on engine capacity: ₹538 for up to 75cc, ₹714 for 75cc to 150cc, ₹1,366 for 150cc to 350cc, and ₹2,804 above 350cc, plus 18% GST.
It’s fixed by IRDAI based solely on engine or motor capacity.
It meets the legal requirement and covers liability to others, but it pays nothing if your own bike is damaged, stolen, or lost. For a bike with real resale value, comprehensive cover offers wider protection.
Yes. A valid third party policy alone satisfies the legal requirement under the Motor Vehicles Act, 1988.
It’s a long-term liability cover bought upfront for new two-wheelers, required since 2018. The Supreme Court’s August 2026 order directs this to move to 6 years once IRDAI issues the implementation rules.
No. Theft of your own bike falls outside third party cover. You would need comprehensive insurance or a standalone own-damage policy for that.
No. This policy only pays for third-party injury, death, or property damage, never your own vehicle.
Yes. You can combine own damage insurance for bike with your existing third party cover to get protection similar to a comprehensive plan.
You can renew third-party bike insurance online by entering your registration or policy number on Coverfox, reviewing the applicable IRDAI rate, paying online, and receiving the renewed policy by email within minutes.
Yes. You can switch to buying or renewing online with Coverfox regardless of how your earlier policy was purchased, as long as you have your registration and previous policy details.
An FIR or other police documentation may be required depending on the nature and circumstances of the accident and the insurer’s claim process.
No. NCB in bike insurance is a discount associated with claim-free own-damage cover. Since third-party premiums are prescribed separately, a third-party claim does not reduce your own-damage NCB.
Since the price is identical across insurers for the same engine capacity, the best third party insurance for a bike comes down to claim support and ease of renewal rather than premium, which is where comparing insurers on Coverfox helps.
A standard third-party bike insurance policy covers the policyholder’s legal liability towards third parties for injuries or death. Personal accident cover in bike insurance for the pillion rider is subject to the policy terms and applicable cover. IRDAI policy wording provides personal accident cover for an unnamed pillion passenger when this cover is opted for with an additional premium.
*Third-party price for an electric bike with a battery under 3 kW (exclusive of GST).
Details on this page is for informational purposes only. Coverage, inclusions, exclusions, add-ons availability, etc are subject to the insurer and the latest IRDAI norms. Refer to your policy document for accurate information.

