- Retail Insurance
- Business Insurance
- Resources
- Claims


The Hero Vida VX2 is an electric scooter from VIDA, Hero MotoCorp's electric mobility brand. It is available with different battery capacities, including 2.2 kWh, 3.4 kWh and 4.4 kWh options. The top-end VX2 Plus 4.4 kWh has a claimed IDC range of up to 187 km and a top speed of 90 km/hr.
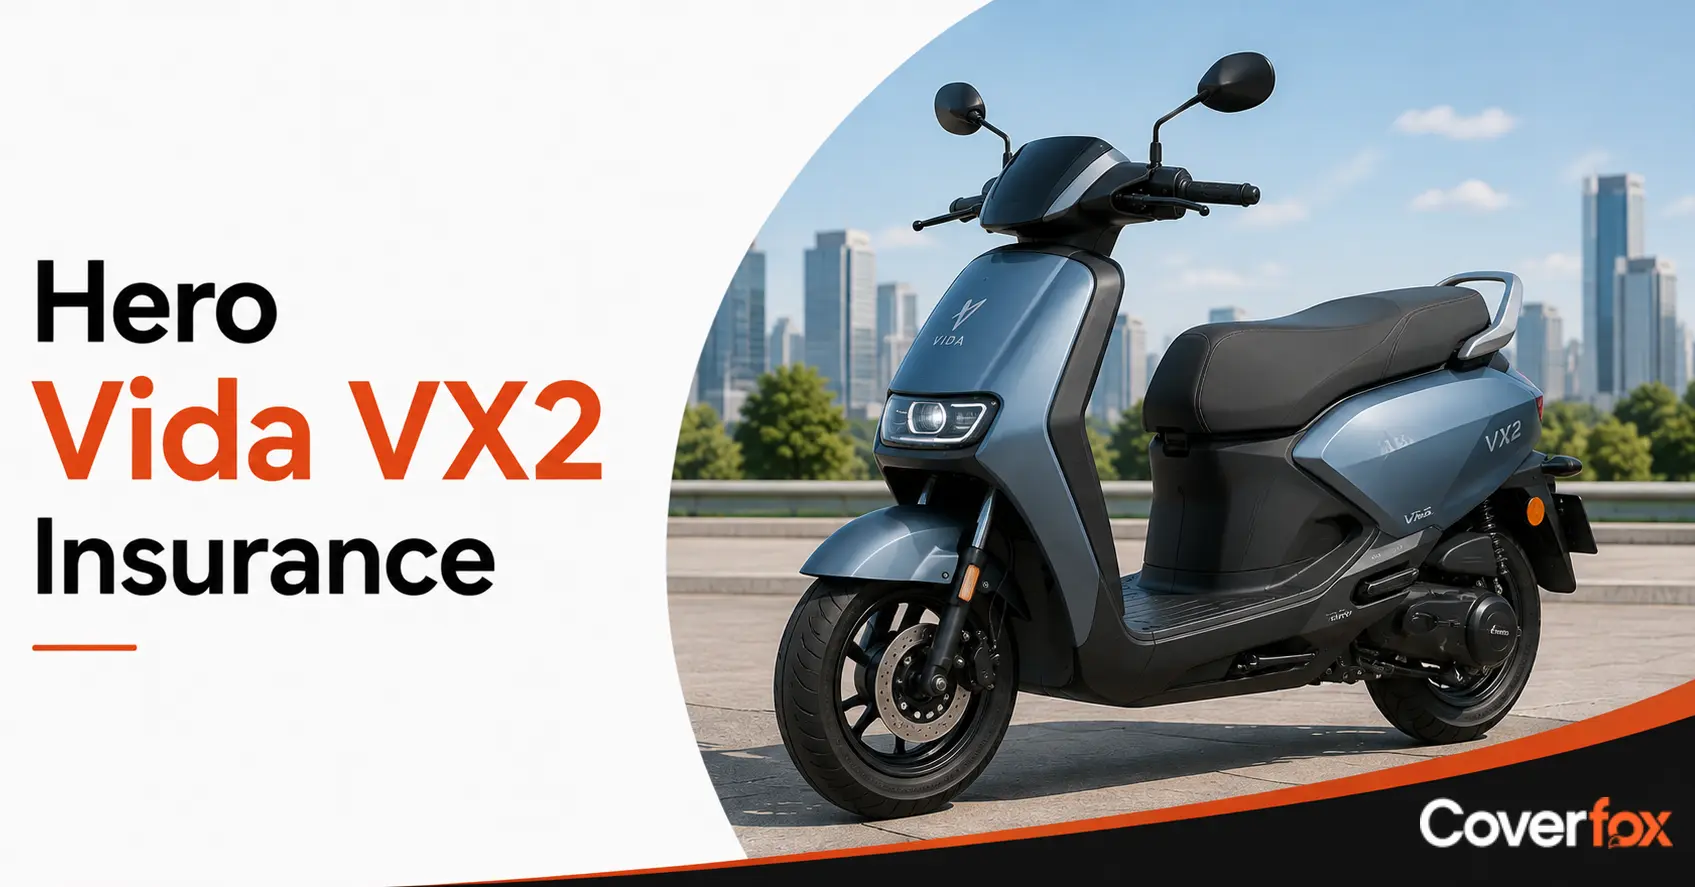
Bike insurance is mandatory for riding the Hero Vida VX2 on public roads. Third-party insurance covers legal liabilities arising from injury, death or property damage caused to another person. A comprehensive policy goes further by covering the scooter against insured risks such as accidents, theft, fire and natural calamities. If you are looking for cover for your VX2, you can compare Electric Bike Insurance options online.
The Hero Vida VX2 insurance premium depends on the variant, IDV, registration location, insurer, policy type and add-ons selected.
| Bike Model | IDV [1st Year] | Zero Depreciation | Net Premium [5 Years] |
|---|---|---|---|
| Vida VX2 Go [2.2Kwh] | ₹66,650 | ₹120 | ₹4,772 |
| Vida VX2 Go [3.4Kwh] | ₹76,532 | ₹137 | ₹4,855 |
Note: Insurance premiums are indicative and vary based on the insurer, registration location, Insured Declared Value (IDV), policy type, vehicle details and selected add-ons. A five-year premium should not be estimated by simply multiplying a one-year comprehensive premium by five.
A higher-priced VX2 variant can have a higher IDV, which can affect the own-damage premium.
The IDV represents the insured value of the scooter for own-damage claims and changes as the vehicle ages.
The location where the VX2 is registered can affect the premium.
Third-party, standalone own-damage and comprehensive policies have different pricing.
Previous claims can affect the premium and No Claim Bonus.
Optional covers increase the premium.
The Vida VX2 is currently available in four versions: Go 2.2 kWh, Go 3.4 kWh, Plus 3.4 kWh and Plus 4.4 kWh. BikeWale's current Bangalore listing also reflects these four variants.
| Variant | Battery Capacity | Claimed Range | Ex-showroom Price* |
|---|---|---|---|
| VX2 Go 2.2 kWh | 2.2 kWh | Up to 92 km | ₹99,490 |
| VX2 Go 3.4 kWh | 3.4 kWh | Up to 142 km | ₹1,04,990 |
| VX2 Plus 3.4 kWh | 3.4 kWh | Up to 142 km | ₹1,09,990 |
| VX2 Plus 4.4 kWh | 4.4 kWh | Up to 157 km | ₹1,13,990 |
*Prices can vary with applicable offers, subsidies and location. The prices above reflect the current figures available in the referenced market listings.
The VX2 was initially introduced with the Go and Plus variants and was later expanded with larger battery options. The 4.4 kWh version is the latest addition to the range.
The VX2 is also available under VIDA's Battery-as-a-Service (BaaS) model. Under this arrangement, the scooter can be purchased at a lower upfront price while battery usage is paid through a separate plan. BikeDekho lists the original BaaS plans for the Go and Plus versions, with the applicable monthly charge depending on the selected kilometre plan.
| Specification | Hero Vida VX2 |
|---|---|
| Motor | Permanent Magnet Synchronous Motor |
| Peak Motor Power | 6 kW |
| Battery Capacity | 2.2 kWh / 3.4 kWh / 4.4 kWh |
| Claimed Range | Up to 187 km, depending on variant |
| Top Speed | Up to 90 km/hr |
| Charging | Removable battery |
| Seat Height | 777 mm |
| Kerb Weight | Varies by variant |
| Display | Digital display |
| Ride Modes | Eco, Ride and Sport, depending on variant |
| Braking System | Drum/disc setup varies by variant |
| Battery Protection | IP67 |
The battery configuration and performance vary across VX2 variants. The larger battery versions provide a higher claimed range, while the Plus variants also get stronger performance and equipment compared with the Go versions.
A valid third-party two wheeler insurance policy is required for the Hero Vida VX2 when it is used on public roads in India. It protects you against specified third-party liabilities arising from an accident.
Third-party insurance, however, does not pay for damage to your own VX2. That is where comprehensive or standalone own-damage insurance becomes relevant.
Covers legal liability for injury, death or property damage caused to a third party, subject to the policy terms.
A comprehensive policy can cover damage to the VX2 caused by an insured accident.
Covers the insured scooter if it is stolen, subject to the policy conditions.
Provides cover for insured events such as floods, storms and other natural disasters.
Covers eligible damage caused by fire and other specified events.
Depending on the policy, certain EV components may receive cover for specified accidental damage.
For a new VX2, comprehensive insurance can make more sense than relying only on third-party cover because it protects the scooter itself as well as third-party liabilities.
A comprehensive Hero Vida VX2 insurance policy combines third-party liability cover with protection against specified damage to the insured scooter.
| Coverage | What it covers |
|---|---|
| Third-party liability | Legal liability arising from third-party injury, death or property damage |
| Accidental damage | Damage to the VX2 caused by an insured accident |
| Theft | Loss of the scooter due to theft |
| Fire | Damage caused by covered fire-related events |
| Natural calamities | Damage caused by covered floods, storms and similar events |
| Man-made events | Damage arising from covered events such as riots or malicious acts |
| Total loss | Settlement based on the applicable IDV and policy conditions |
Battery cover needs to be checked separately in the policy wording.
Damage to the battery resulting from an insured accident may be covered under the policy. However, normal battery deterioration, loss of capacity, wear and other excluded conditions are not treated as accidental damage.
The manufacturer's warranty is different from insurance. A warranty deals with eligible product or manufacturing-related issues, while insurance responds to specified insured events.
You do not need every available two-wheeler add-on for the VX2. A few are more relevant to an electric scooter.
Reduces depreciation deductions on eligible parts replaced during an admissible claim, subject to the insurer's terms. This can help reduce the amount you have to pay towards a repair.
Provides help for situations such as breakdowns, towing and other eligible roadside emergencies. It can be useful if the VX2 cannot be ridden after an accident or develops a breakdown.
Can bridge the difference between the vehicle's IDV and its invoice value if the scooter is stolen or declared a total loss, subject to the add-on conditions.
Provides additional protection for the battery against specified risks where the insurer provides this cover. Check whether the policy covers accidental battery damage, water-related damage and other specified events before purchasing.
The availability of these add-ons varies between insurers. The terms, exclusions and claim limits should be checked before selecting them.
You can buy or renew Hero Vida VX2 insurance online by entering the scooter details, selecting the required cover and comparing available policies.
Provide the VX2 registration number and other required details.
Choose the correct VX2 variant.
Select third-party, standalone own-damage or comprehensive insurance.
Review the IDV quoted for the scooter.
Check premiums, coverage, deductibles and available add-ons.
Choose only the additional covers relevant to your usage.
Provide the required personal and vehicle information.
Complete the transaction online.
Save the policy document for future reference.
You can also compare Hero Vida Insurance options through Coverfox.
Renewal is straightforward if the existing policy details are available.
Renew before the policy expires to avoid a break in coverage.
Make sure the quoted IDV is appropriate for the scooter.
Verify that the applicable No Claim Bonus has been carried forward correctly.
Remove covers you no longer need and retain those that are relevant.
Look at the coverage and deductible along with the price.
Pay the renewal premium and download the renewed policy.
Yes: You can purchase a policy online after entering the required vehicle details, selecting the cover and completing payment. The policy issuance process can vary between insurers.
Comprehensive insurance: For a new VX2, comprehensive cover gives protection for both third-party liability and damage to your own scooter. A third-party policy alone does not cover accidental damage to the VX2.
Yes: Comparing insurers lets you look at premium, IDV, deductibles, coverage and add-ons before making a decision. The cheapest quote is not necessarily the most suitable policy if it comes with a lower IDV or fewer useful covers.
NCB: A break in the policy can affect your No Claim Bonus. IRDAI states that an accrued NCB is lost if a comprehensive policy is not renewed within 90 days of its expiry. Renewing before expiry avoids this situation.
The claim process depends on whether the repair is being handled through a network garage or on a reimbursement basis.
Inform the insurer about the accident or insured event.
Arrange towing or roadside assistance if the VX2 cannot be ridden.
Take the scooter to an insurer-authorised garage.
Provide the policy and vehicle documents requested by the insurer.
The insurer assesses the damage before approving the repair.
The approved repairs are carried out by the garage.
The insurer settles the admissible repair cost directly with the network garage after applicable deductions.
Register the claim and follow its instructions.
Complete the required inspection before repairs where applicable.
Pay the repair bill as required under the reimbursement process.
Keep the original bills, receipts and repair records.
Provide the required documents to the insurer.
The insurer checks the damage, policy coverage and submitted bills.
The admissible amount is paid after applicable deductions.
Confirms the insurance cover and policy details.
Establishes the vehicle and ownership details.
Confirms that the rider was legally permitted to ride the scooter.
Contains details of the accident or insured event.
Shows the expected repair cost.
Required for reimbursement claims.
May be required for theft and certain accident-related claims.
May be requested for theft claims.
May be required for reimbursement settlement.
The insurer can request additional documents depending on the nature of the claim.
Yes. Third-party insurance is mandatory for the Hero Vida VX2 when it is used on public roads in India. A comprehensive policy is optional but also covers damage to your own scooter.
The cost depends on the VX2 variant, registration location, IDV, insurer, policy type and selected add-ons. For example, BikeWale lists ₹6,560 as the comprehensive insurance component for the VX2 Go 2.2 kWh in Bangalore. This figure can vary by location and insurer.
You can choose from third-party, standalone own-damage and comprehensive insurance. Third-party insurance covers liabilities towards others, while standalone own-damage covers damage to your scooter. Comprehensive insurance combines both types of protection.
A comprehensive policy can be a suitable choice for a new Hero Vida VX2 as it covers third-party liabilities as well as damage to the scooter. You can also add covers such as Zero Depreciation or EV battery protection based on your requirements.
Battery damage may be covered if it results from an insured event, depending on the policy terms. Normal battery degradation, wear and tear and loss of battery capacity are not automatically covered. Check the insurer's EV-specific coverage before purchasing.
Insurance and warranty cover different risks. The manufacturer warranty covers eligible product or manufacturing-related issues, while insurance covers specified events such as accidental damage. The exact warranty terms and insurance coverage should be checked separately.
Yes, you can renew Hero Vida VX2 insurance after the policy expires. However, the insurer may require a vehicle inspection before issuing the renewed policy. A delay can also affect your No Claim Bonus, so renewing before expiry is advisable.
IDV, or Insured Declared Value, is the maximum amount payable for the scooter in cases such as theft or total loss, subject to the policy terms. It is calculated based on the vehicle's value after applicable depreciation and decreases as the scooter ages.

